Fintech · Industry brief
Top three stories shaping Fintech today, written for someone who already works in the industry: regulation, M&A, new entrants, notable filings, and any precedent worth pulling. Cite the trade publication (e.g. trade press, government source, court docket) directly so I can follow up.
← Zur aktuellen AusgabeDe novo boom stalls; third-party risk rules ease; AML crackdown tightens
De novo chartering plateau
The de novo surge is hitting a structural ceiling, not just regulatory hurdles.
While Trump administration approvals jumped to seven new banks in 2026 (five in 2025), a Federal Reserve Bank of Kansas City study shows the decades-long decline in new bank formation stems from technological and market shifts, not regulation alone [Source: American Banker]. Even aggressive deregulation would only add five or six charters annually, nowhere near pre-2008 levels of 185 per year. Today's de novo applicants are fintech-backed trust and payments firms, not community lenders—a market reshuffling that regulatory relief cannot reverse.
The wave is narrower and more specialized than the industry expected.
Third-party risk rules soften
Regulators just backed away from prescriptive vendor oversight.
On September 11, the OCC, Federal Reserve, FDIC, and NCUA jointly proposed revised third-party risk guidance rescinding the 2023 playbook they now admit was read too literally [Source: Skadden]. The new framework emphasizes magnitude and likelihood of harm, permits streamlined reviews for lower-risk vendors, and lets banks rely on shared assessments instead of conducting duplicate due diligence. Examiners will defer to banks' own risk judgments if supported by objective facts. Comments close November 16.
Expect fintech service providers to see faster vendor qualification cycles.
FCA escalates AML enforcement
U.K. regulators are now investigating fintech firms for systemic AML lapses.
The FCA opened an enforcement probe Thursday into Euro Exchange Securities Ltd, a fintech the agency seized earlier this month [Source: ACAMS]. The move signals a shift from soft compliance guidance to active gatekeeping—regulators are treating AML deficiencies as deal-breakers for both new charters and operating licenses. Fintech teams should audit transaction monitoring and identity verification infrastructure now.
AML rigor is becoming the filtering layer for market entry.
Europe signals competitive relief
The EU and U.K. are proposing targeted regulatory easing to shore up bank competitiveness.
The European Commission and UK authorities unveiled measures to improve capital-buffer usability and market-risk model practicality, part of a wider governance initiative led by the DPM Alliance (EBA, ECB, EIOPA) established in 2024 [Source: Fitch Ratings]. The changes are expected to support consolidation and lending capacity while maintaining credit stability. A parallel effort to overhaul regulatory reporting (led by FinTech Global) will reshape how banks file data upstream.
Watch for M&A activity to accelerate once capital rules clarify.
 FCA Probes Fintech Over Systemic AML Breaches - ACAMS14 hours ago ... The U.K. Financial Conduct Authority on Thursday opened an enforcement investigation into Euro Exchange Securities Ltd, a fintech seized by regulators in ...acams.org
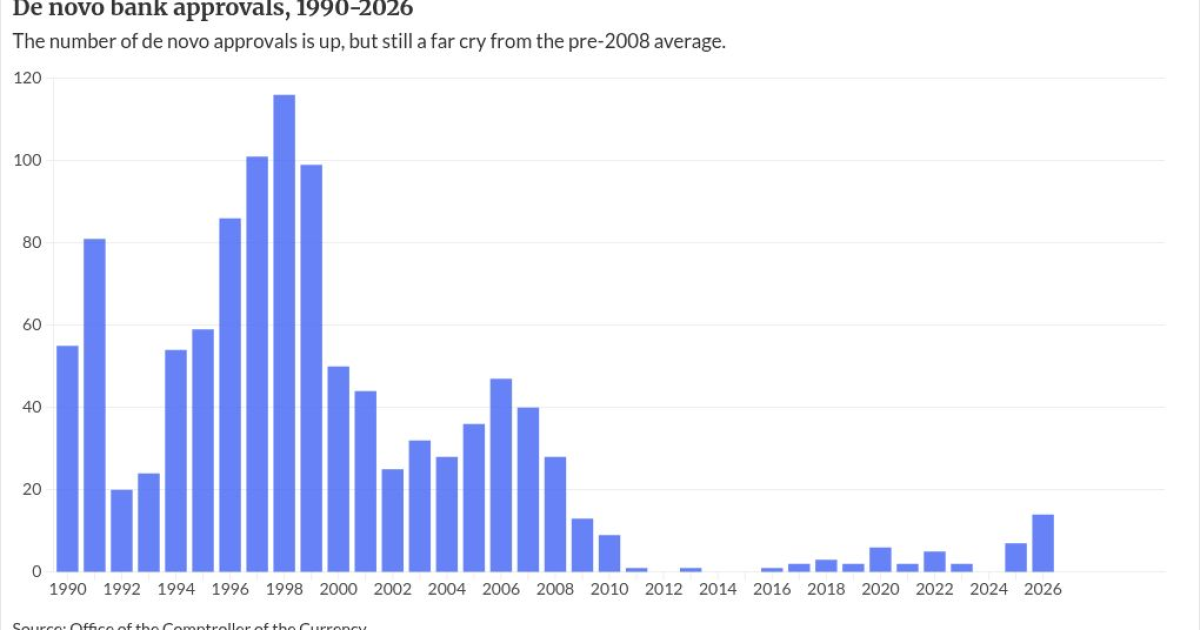 De novo applications are up, but the tide isn't turning back8 hours ago ... ... regulation in the wake of the financial crisis stifled new bank formation. ... regulatory burden has "undoubtedly led" to bank consolidation. "Banking ...americanbanker.com
 Global Banking Regulatory Developments 3Q269 hours ago ... These changes could support bank consolidation and lending capacity, while ... Structured Finance 2025 Transition and Default Study. About. About Us ...fitchratings.com
 US Federal Banking Agencies Propose Revised Third-Party Risk ...22 hours ago ... ... compliance with laws and regulations, and resource allocation. The issuance ... filings or supervisory examination reports for certain large service ...skadden.com