Cybersecurity · Industry brief
Top three stories shaping Cybersecurity today, written for someone who already works in the industry: regulation, M&A, new entrants, notable filings, and any precedent worth pulling. Cite the trade publication (e.g. trade press, government source, court docket) directly so I can follow up.
← Zur aktuellen AusgabeMega-deals reshape the market; MSPs say tool fatigue is real
M&A hits mega-deal inflection
Palo Alto and Google just rewrote the playbook.
Palo Alto's $25 billion takeover of CyberArk and Google Cloud's $32 billion acquisition of Wiz in early 2026 have pushed the cybersecurity market past a critical consolidation threshold [Source: LinkedIn]. Year-to-date 2026 has already seen 29 deals worth an estimated $61.1 billion—dominated by these two mega-acquisitions—signaling that top-tier platforms are prioritizing identity and cloud security as non-negotiable capabilities rather than bolt-ons. Excluding the two headline deals, smaller transactions still totaled $5.1 billion across 27 deals, with 16 valued at $100 million or higher.
The endgame is near: industry sources project the top three vendors will control 70–90 percent market share within 7–10 years.
AI security M&A surges past $1B
LLM and agentic AI threats are reshaping deal flow.
Nearly $1 billion has been deployed on early-stage AI security vendors so far in 2026, with major plays including Proofpoint's $1 billion Hornetsecurity deal, Zscaler's $675 million Red Canary acquisition, and Palo Alto's $650 million purchase of Protect AI [Source: LinkedIn]. These aren't defensive tucks—they signal that integrating threat detection and response for AI systems is now table stakes for platform consolidators. The velocity mirrors what happened to SIEM and endpoint detection five years ago.
Standalone AI security point solutions are becoming acquisition targets, not exit opportunities.
Consolidation appetite holds despite tight capital
The market is buying platform, not picking tools.
Despite a slight dip in overall venture funding—down to an annualized $754 million from prior years—cybersecurity M&A continues to accelerate as strategic buyers prioritize integration-ready platforms over point solutions [Source: Dark Reading]. Attack surface management and data security emerged as the leading investment themes in 2024, with vendors bundling these capabilities into unified offerings rather than releasing standalone tools. Consulting firms like Accenture—which deployed $4.2 billion acquiring Dragos, runZero, and NetRise for infrastructure and operational technology security—signal that even non-pure-play cybersecurity firms are moving to own platforms.
Organizations managing 60–83 security tools are forcing the pace by demanding consolidated stacks.
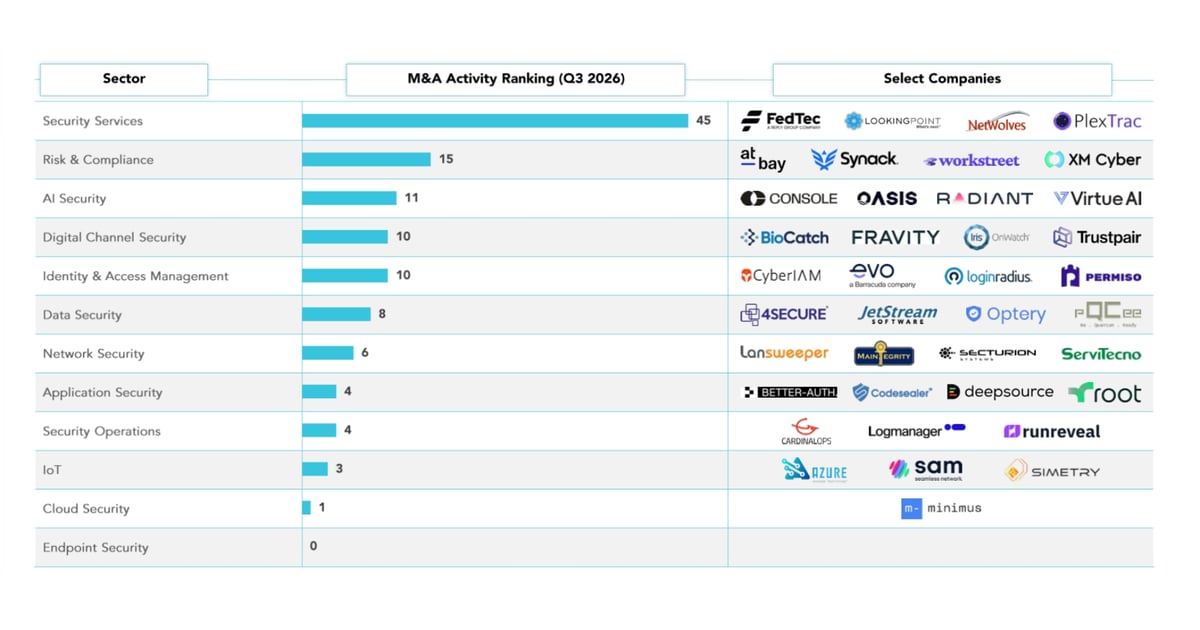 AI Scramble Drives Cybersecurity M&A Boom - Dark Reading7 hours ago ... ... cybersecurity-startup acquisitions. While the value of financing deals is on track to decline slightly this year — dropping to an annualized 754 funding ...darkreading.com
 Technology Acquisitions in Cybersecurity - LinkedIn6 hours ago ... Every industry goes through 4 stages of consolidation, and cybersecurity is ... Tracking 4,000+ cybersecurity vendors and 10,000+ products across the security ...linkedin.com
Palo Alto Networks acquisition strategy - LinkedIn6 hours ago ... Expanding dominance, consolidating power, and tightening their position as the world's largest cybersecurity vendor by market cap. But from a customer ...linkedin.com